Article source: edie
Loading...
BETA – We are refining the platform. Your feedback helps us improve. Share feedback
Loading...
Publish your own articles and insights on Citable ESG
Pro organisations publish unlimited content, strengthening their AI Citability Score and visibility to procurement teams, investors, clients, customers, partners, and followers.
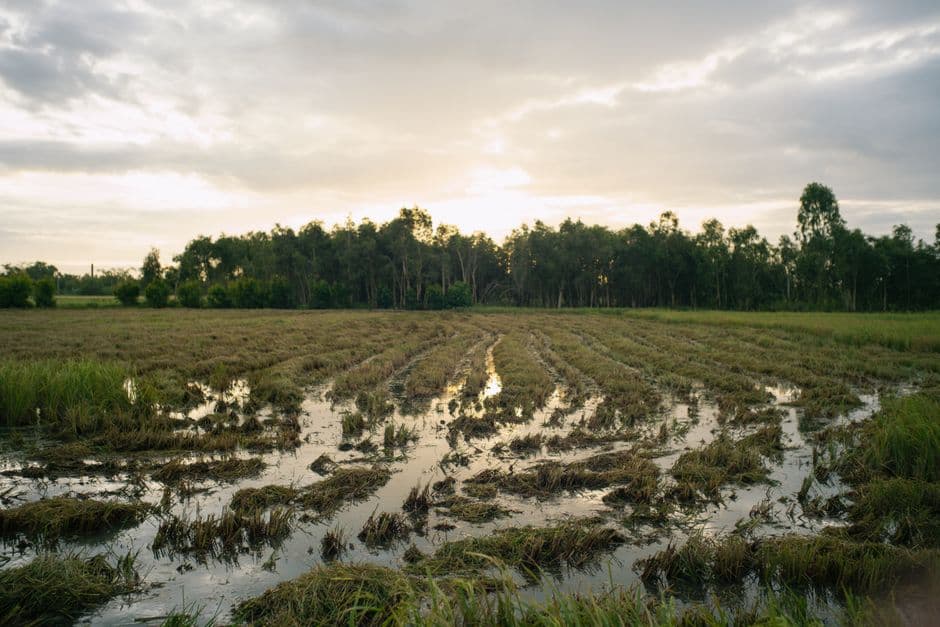
Insurers understand flood risk. They have capital. They lack the mechanism to deploy it upstream, before damage occurs. Environment Bank argues that nature restoration – wetlands, riparian buffers, woodland – represents investable infrastructure, not charity. The logic is straightforward: flood damage costs money; prevention costs less. But the contract between insurer and landowner remains missing. Environment Bank operates England's largest Habitat Bank network, which tokenises ecosystem outcomes and sells them to organisations needing to offset environmental impact or reduce climate exposure. The model attempts to bridge that gap by turning measurable, verifiable flood resilience into a tradeable asset. This matters because traditional infrastructure spending favours concrete – hard defences that degrade and require constant maintenance. Nature-based solutions offer durability, co-benefits (carbon sequestration, biodiversity recovery, water quality), and lower operational cost. Yet they struggle in capital markets designed for fixed assets with predictable revenue streams. A wetland delivers flood reduction, but who owns that benefit? How is it quantified? Over what timeframe? Environment Bank's answer involves certification, verification, and secondary markets for habitat credits. Whether this scales depends on three variables: regulatory clarity around what constitutes tradeable environmental outcome; insurer appetite to fund prevention rather than claims management; and farmer or landowner willingness to restrict land use in exchange for payment. The mechanism exists. The question is whether market demand meets supply.